Eurex Clearing Prisma
Eurex Clearing Prisma determines risks across markets and venues cleared by Eurex Clearing with the most noteworthy segments being listed derivatives, OTC derivatives and fixed income securities settlements.
Prisma calculates margin requirements at the portfolio level for all customer and proprietary portfolios, recognizing risk offsets across economically related products. This delivers significant capital efficiency for clearing members and their clients while maintaining a robust risk management framework.
Risk Model Paradigm
Risks are assessed jointly for products sharing similar risk characteristics within the demarcation of Liquidation Groups and Splits resulting in holistic risk estimates. The estimation of risk employs the concepts of portfolio- and cross margining.
- Portfolio margining is applied to products within the same Liquidation Group Split, sharing a common holding period, e.g. EURO STOXX 50® Index and DAX® Futures or amongst fixed income securities. Portfolio margining offers significant margin efficiencies for diversified portfolios.
- Cross margining is applied to products across markets that are part of different Splits, due to varying holding periods, within a given Liquidation Group, as observed in the fixed income offering. Cross margining allows for offsets between such different Splits and is offered between OTC IRS (5 day holding period) and listed fixed income products (2 day holding period). A reduced risk profile of an interest rate-hedged portfolio is therefore adequately reflected by a lower initial margin requirement.
The overall methodology is designed to foster accuracy and stability, ensuring that resulting margins withstand emerging shocks and changes to the financial markets while still allowing for adaptation to overall changes in the risk environment.
Advantages for Clearing Members, their customers and the Clearing House
- Capital efficiency: accurate and consistent risk netting effects allow for lower initial margins for hedged portfolios.
- Accuracy: simulations capture accurate profit and losses per product, netted within the portfolio.
- Robustness: methodology designed to enable stable and efficient margin requirements incorporating anti-procyclicality buffers.
- Consistency: coherent simulation of risk factor dynamics captures consistent profit and losses across various products and unlocks portfolio diversification effects.
- Automation: automated processes supporting faster time-to-market.
- Alignment: margining methodology is built upon the foundation of the default management.
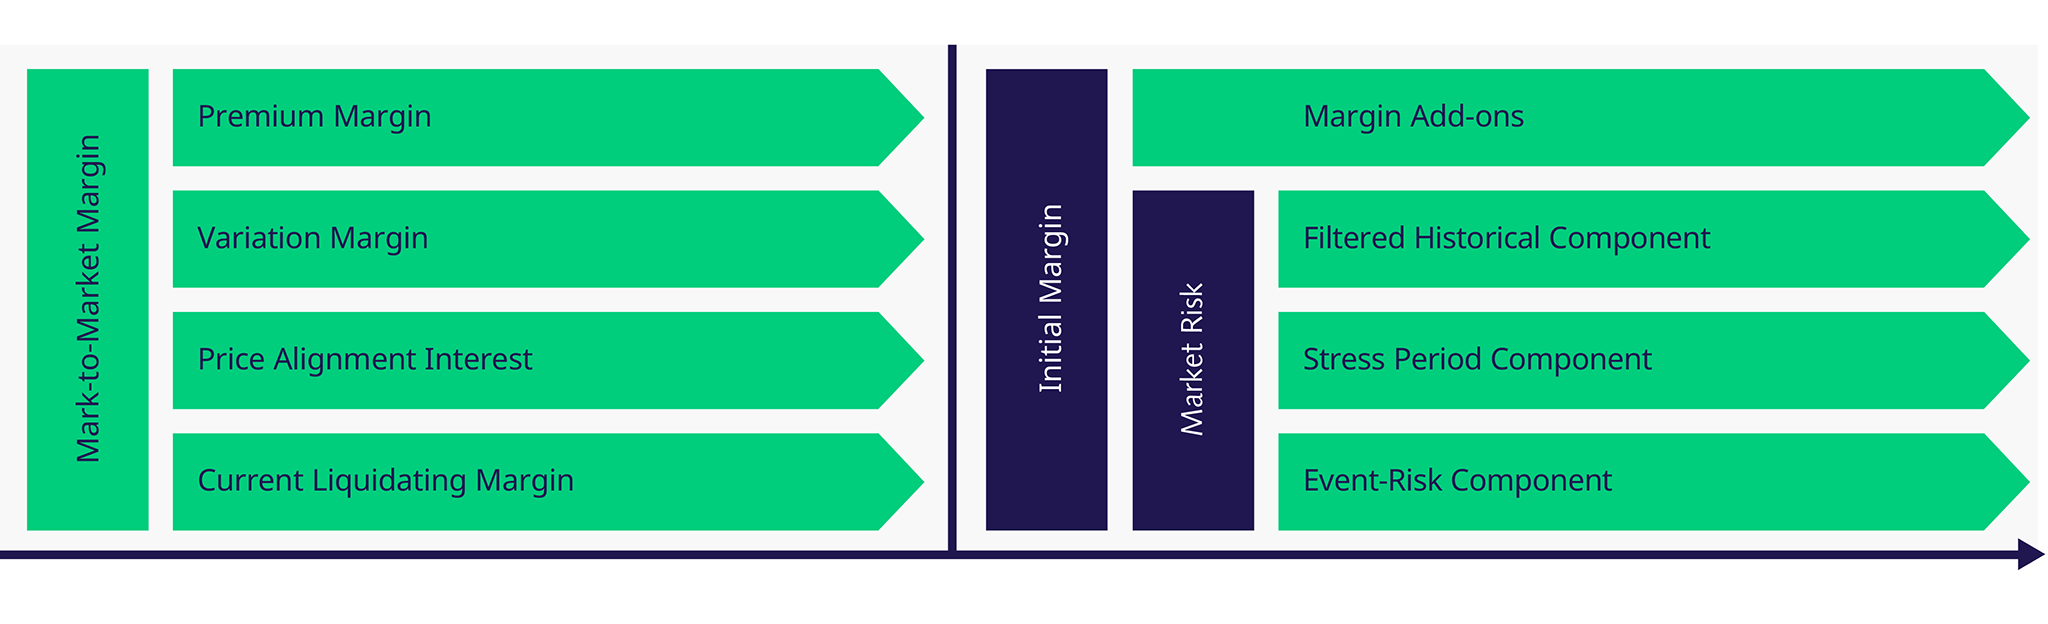
Margin Components
The elements in the concept are selected so that risk calculation is accurate and stable, ensuring that the concept withstands new shocks and changes to the financial markets and flexibly adapts to changes in the risk environment.