Key Benefits
Why do market participants clear at Eurex?
|
Market Statistics
A leading EU-based liquidity pool for OTC IRD
Eurex has established a robust and growing liquidity pool for OTC IRD. Supported by a broad network of clearing members, liquidity providers, execution venues and clients, Eurex is the Home of the Euro Yield Curve and a leading EU-based venue for OTC IRD clearing.
As participation continues to grow, market participants benefit from increasing liquidity, transparent pricing and an integrated clearing ecosystem spanning OTC, listed and repo markets. Learn more: OTC IRD Partnership Program and CCP Switch
Average daily volume cleared
1 Due to tri-party multilateral portfolio compression, new trades have been opened at Eurex Clearing AG, resulting in total of 211bn Euro in August 2025, 207bn Euro in September 2025, 336bn Euro in November 2025, 257bn Euro in December 2025, 221bn Euro in January 2026, 213bn Euro in March 2026, 267bn Euro in April 2026, 352bn Euro in May 2026, 259bn Euro in June 2026, 237bn Euro in July 2026 and 346bn Euro in August 2026.
IRS & OIS average daily volume cleared
Notional outstanding
* Source: Clarus FT
For more data, please go to Clearing volumes
Eurex-LCH basis
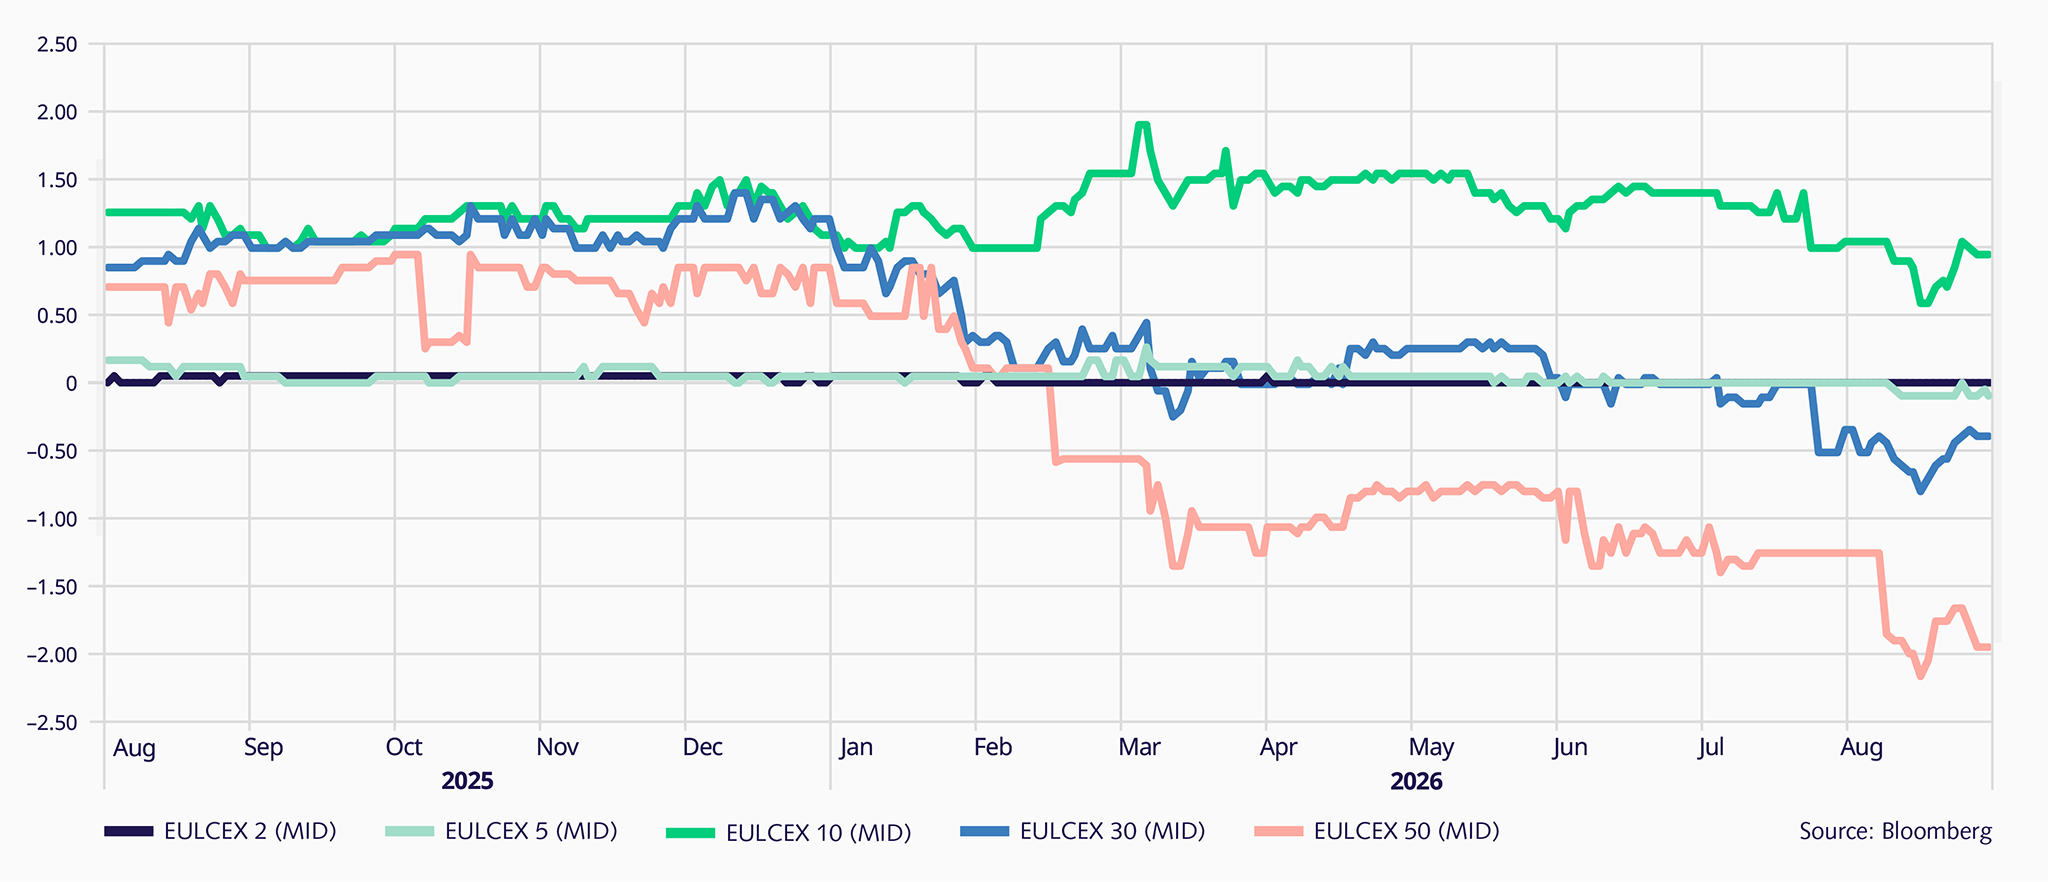
Learn more: Eurex-LCH Basis and Portfolio Balance
Product Scope
Central clearing of OTC IRD and inflation swaps
Eurex Clearing supports the central clearing of OTC IRD across 11 currencies and of inflation swaps. Through a single clearing ecosystem, participants can consolidate risk, streamline operations and benefit from capital, margin, collateral and operational efficiencies.
Type | Currencies | Maturity | Supported types | Other characteristics |
IRS | EUR | 61 years (22,335 days) | Plain vanilla (fixed/float) Basis/tenor (float/float) | ISDA, German framework agreements Constant notionals Front, end stubs, forward starts 1m, 3m, 6m, 12m – EUR (EURIBOR) 3m, 6m – DKK (CIBOR), NOK (NIBOR), PLN (WIBOR), CZK (PRIBOR), HUF (BUBOR) 3m – SEK (STIBOR) 1d – EUR (€STR), GBP (SONIA), USD (SOFR, Fed Funds), CHF (SARON), JPY (TONA), DKK (DESTR), PLN (POLSTR) Zero coupon Variable notional – amortizing & roller coaster Negative interest rates and spreads IMM roll dates Variable spreads & fixed coupons Compounding |
USD | 51 years (18,675 days) | Basis/tenor (float/float) | ||
DKK, NOK | 31 years (11,375 days) | Plain vanilla (fixed/float) Basis/tenor (float/float) | ||
SEK | 31 years (11,375 days) | Plain vanilla (fixed/float) | ||
CZK, HUF, PLN | 16 years (5,871 days) | Plain vanilla (fixed/float) Basis/tenor (float/float) | ||
OIS | EUR | 61 years (22,335 days) | Plain vanilla (fixed/float) | |
GBP, USD | 51 years (18,675 days) | Plain vanilla (fixed/float) | ||
CHF, JPY | 31 years (11,375 days) | Plain vanilla (fixed/float) | ||
DKK | 11 years (4,050 days) | Plain vanilla (fixed/float) | ||
PLN | 16 years (5,871 days) | Plain vanilla (fixed/float) | ||
FRA | EUR, DKK, NOK, SEK, PLN, CZK, HUF | 3 years (1,225 days) | Plain vanilla (fixed/float) |
Type | Underlyings | Start dates | Max. maturities | Indexing lags | Index levels | Market data |
Zero-Coupon Inflation Swap | HICPxT (Eurozone) FRCPI (France) UKRPI (UK) | Spot starting (EUR/French: T+2, UK: T+0) Past starting (for novated trades) | UKRPI / HICPxT: 50Y FRCPIx: 30Y | 2-12 whole months | Monthly and daily interpolation | Par-swap rates (Member quoted via Bloomberg, Reuters intra-day, Backup via Broker Quotes)
|
Standard Coupon Inflation Swap | HICPxT (Eurozone) | Spot starting (EUR: T+2) Past starting (for novated trades) | HICPxT: 50Y | 2-12 whole months | Monthly and daily interpolation |
For further information, please refer to the EurexOTC Clear Product list. The detailed product level eligibility can be found in the Member Section under Resources > Eurex Clearing > Documentation & Files > EurexOTC Clear > System Documentation > Overview, or alternatively on Eurex Clearing Rules & Regulations under 1. Clearing Conditions > Chapter VIII Part 2.
Of the above mentioned list of clearing eligible products, and as required by CFTC Rule 39.21(c)(8), Eurex Clearing AG identifies that it clears the following interest rate derivatives listed in the Tables of CFTC Rule 50, which fall under the CFTC’s mandatory clearing requirement:
- Fixed-to-floating: EUR, NOK, SEK, PLN
- Basis: EUR, USD
- Forward rate agreement: EUR, NOK, SEK, PLN
- Overnight index: EUR, GBP, USD
Of the above mentioned list of clearing eligible products, and as described under Canadian National Instrument 94-101, Eurex Clearing AG identifies that it clears the following interest rate derivatives listed in Appendix A NI 94-101, which fall under the Canadian mandatory clearing requirement:
- Fixed-to-floating: EUR
- Basis: EUR
- Forward rate agreement: EUR
- Overnight index: GBP, USD
Prisma
How does Eurex Clearing Prisma help optimize margin requirements?
Eurex Clearing Prisma is Eurex's portfolio-based risk management methodology. By recognizing offsets between correlated positions, Prisma helps participants optimize margin requirements and use capital and collateral more efficiently across their cleared portfolios. Learn more: Eurex Clearing Prisma
Access
How can you access Eurex OTC Clear?
Eurex offers a range of access models designed to meet the needs of banks, asset managers, pension funds, insurers and other institutional market participants. Through a broad clearing member network and dedicated onboarding support, participants can seamlessly connect to the Eurex OTC Clear ecosystem. Learn more: ISA Direct and Membership Types